


One question comes up in almost every conversation we have with a prospective buyer abroad, usually somewhere around the second or third phone call: how do people actually pay for property here? It is a fair question, and a surprisingly under-discussed one. Most of what gets written about buying in Antigua focuses on the legal steps — the Land Holding Licence, the Citizenship by Investment route, the closing process — and understandably so. But financing is where the plan either comes together or stalls, and it works a little differently here than it might in your home market. This week, we are setting aside the legal mechanics to look specifically at how overseas buyers fund their Antigua purchase, from cash to cross-border mortgages to developer payment plans.
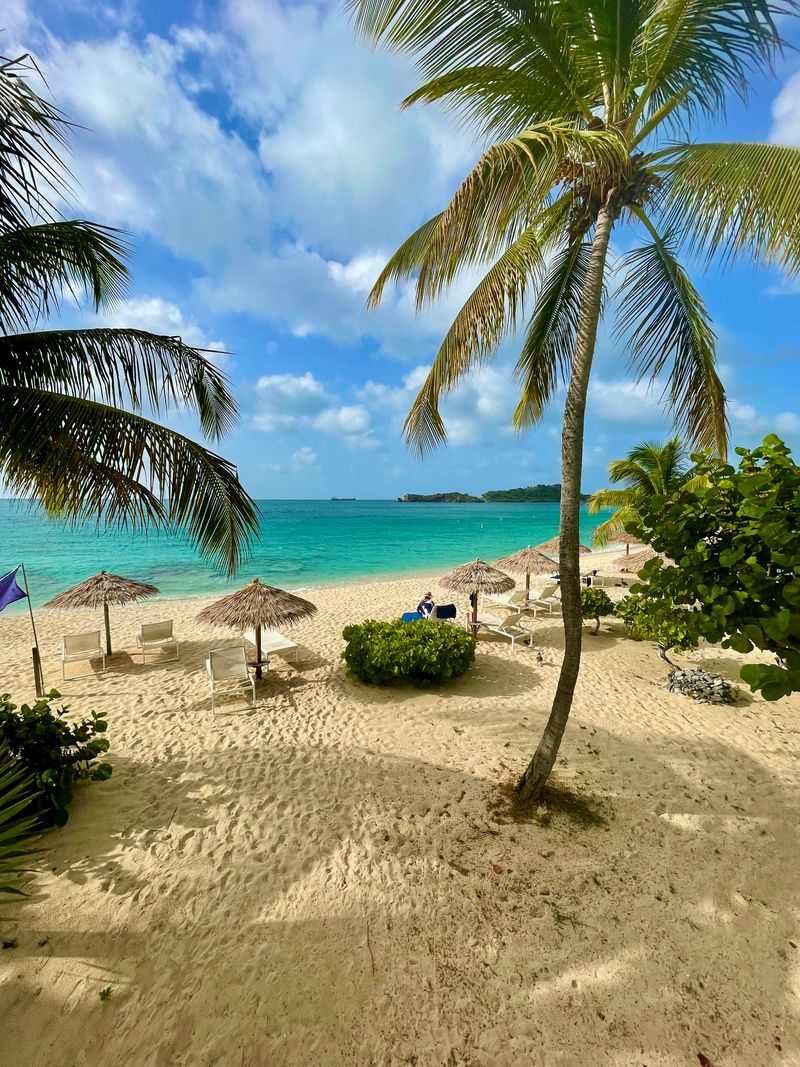
Cash Still Rules, But It Is Not the Only Option
A larger share of international real estate transactions in Antigua are completed in cash than you would typically see in, say, the United States or the United Kingdom. There are a few reasons for that. Many overseas buyers here are purchasing a second home or an investment property rather than a primary residence, which tends to draw buyers who are further along in their financial lives and simply prefer the speed and certainty of a cash close. Cash also sidesteps a layer of cross-border lending complexity that can slow things down, and it strengthens your negotiating position considerably — sellers and developers alike tend to move faster, and sometimes more flexibly on price, for a buyer who is not waiting on a loan approval.
That said, a cash purchase is a choice, not a requirement. Financing is available, it simply tends to come from one of three directions rather than a single standardized path: a local Antiguan bank, a lender back in your home country, or the developer itself. Each has a different rhythm, and the right one for you often depends less on which is “best” in the abstract and more on where your existing financial relationships already sit.
Financing Through a Local Bank
Several banks operating in Antigua and Barbuda do extend mortgage financing to non-citizens, though the terms are generally more conservative than what a resident borrower would be offered. It is commonly reported that overseas buyers should expect a larger down payment than they might be used to at home — often in the range of 30 to 50 percent of the purchase price — along with shorter amortization periods and interest rates that run higher than typical rates in North America or the UK. None of those figures are fixed, and they move with regional banking conditions, so treat any number you hear, including the ranges above, as a starting point for a conversation rather than a quote you can bank on.
Local financing has a genuine advantage worth weighing: the loan is denominated in Eastern Caribbean dollars, a currency pegged to the US dollar, which removes exchange-rate volatility from your repayment calculations if your income is also in or linked to US dollars. Banks will typically want to see proof of income, bank reference letters, a clean credit history, and sometimes a local guarantor or additional collateral, and the underwriting process can take noticeably longer than buyers are used to at home. Building in extra time — and keeping your sale agreement structured so your deposit is protected if financing falls through — is simply part of planning a locally financed purchase here.
Questions worth asking a local lender early
- What loan-to-value ratio will they actually offer a non-resident buyer, as opposed to the headline figure quoted to local borrowers.
- Whether the interest rate is fixed or variable, and how often a variable rate can reset.
- What documentation they require from an overseas applicant, including whether it needs to be notarized, apostilled, or translated.
- How the mortgage interacts with your Land Holding Licence or CIP application, since both processes typically need to be tracked on parallel timelines rather than assumed to run independently.
Financing From Your Home Country
A good number of overseas buyers choose a route that never touches an Antiguan bank at all: borrowing against assets or property they already hold at home. A home equity line of credit, a portfolio-backed loan from a private bank or brokerage, or a cash-out refinance on an existing property can all fund an Antigua purchase in cash from the seller’s perspective, even though you are technically carrying debt back home. This approach tends to be faster to arrange, because you are working with lenders who already know you, and it can come with more competitive interest rates than a local mortgage, particularly if you have an established private banking relationship.
The trade-off is currency exposure. If you are borrowing in your home currency to buy a property priced in US dollars (or Eastern Caribbean dollars, pegged to the US dollar), you are taking on an implicit currency position for as long as that loan is outstanding. For US-based buyers this is a non-issue given the peg, but for buyers coming from the UK, Canada, or the eurozone, it is worth running the numbers both ways and, if the amounts are significant, having a conversation with a currency specialist about hedging or timing your transfer around favorable exchange rates rather than wiring funds the moment you are ready emotionally.
Developer and Vendor Financing
For buyers purchasing into a newer development, particularly one still under construction, a number of developers offer their own staged payment plans as an alternative to a traditional mortgage. These typically work on a milestone basis — a deposit to reserve the unit, followed by further installments tied to construction progress, with a final payment due at or near completion. It is a financing structure that suits buyers who would rather spread payments over the build timeline than either tie up a large lump sum upfront or go through a bank’s underwriting process.
If you are considering this route, a few habits protect you well. Ask exactly what happens to your payments if construction is delayed or the project does not complete on schedule, and whether funds are held in an escrow or stakeholder account rather than going directly to the developer’s operating accounts. Have your attorney review the payment schedule against the development’s actual construction permits and track record, not just its marketing materials, and confirm in writing how the payment plan interacts with any Land Holding Licence or CIP timeline, since those approvals sometimes need to be in hand before certain milestone payments are due.
Budgeting for What Financing Does Not Cover
Whichever route you take, it helps to think of the purchase price as the headline number rather than the full cost of ownership. Stamp duty, legal fees, and licence or programme fees sit outside the financed amount and are typically due in cash at various points in the process. If you are financing locally, your lender will usually want to see that you have these costs covered separately rather than folded into the loan. If you are borrowing from home, it is worth confirming your facility actually covers these ancillary costs and not just the headline purchase price, since underestimating them is one of the more common surprises overseas buyers report after closing.
It is also worth having a frank conversation with your lender, wherever they are based, about ongoing carrying costs once the keys are in hand — property insurance appropriate for a hurricane-exposed Caribbean property, any applicable property taxes, and a maintenance reserve for a home exposed to salt air and tropical humidity. None of this is unique to financed purchases, but a lender evaluating your application will often want to see that you have budgeted for it, and it is simply good practice regardless of how you pay.
A Few Principles That Tend to Serve Buyers Well
Across the different financing paths, a handful of habits come up again and again among buyers who look back on the process as having gone smoothly. Get pre-qualified, or at least have a candid conversation about your likely terms, before you fall for a specific listing, so your offer is grounded in what you can actually arrange rather than what you hope to arrange. Involve your attorney in reviewing any financing or payment structure before you sign, not after, since Antiguan contract conventions are not always identical to what you are used to at home. And treat every rate, ratio, and fee you read anywhere, including in this article, as commonly cited rather than guaranteed — terms move with market conditions, and a conversation with a local bank, your own financial institution, or a cross-border mortgage broker will always be more current than anything in print.
However you end up funding it, there is a particular kind of satisfaction in watching a financing structure you built carefully — across two countries, two currencies, sometimes two banks — finally resolve into a single set of keys and a quiet view of the water. The paperwork is never quite as romantic as the island itself, but it is what makes the romantic part last.